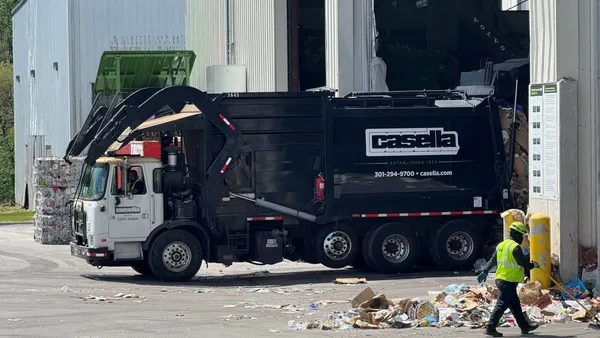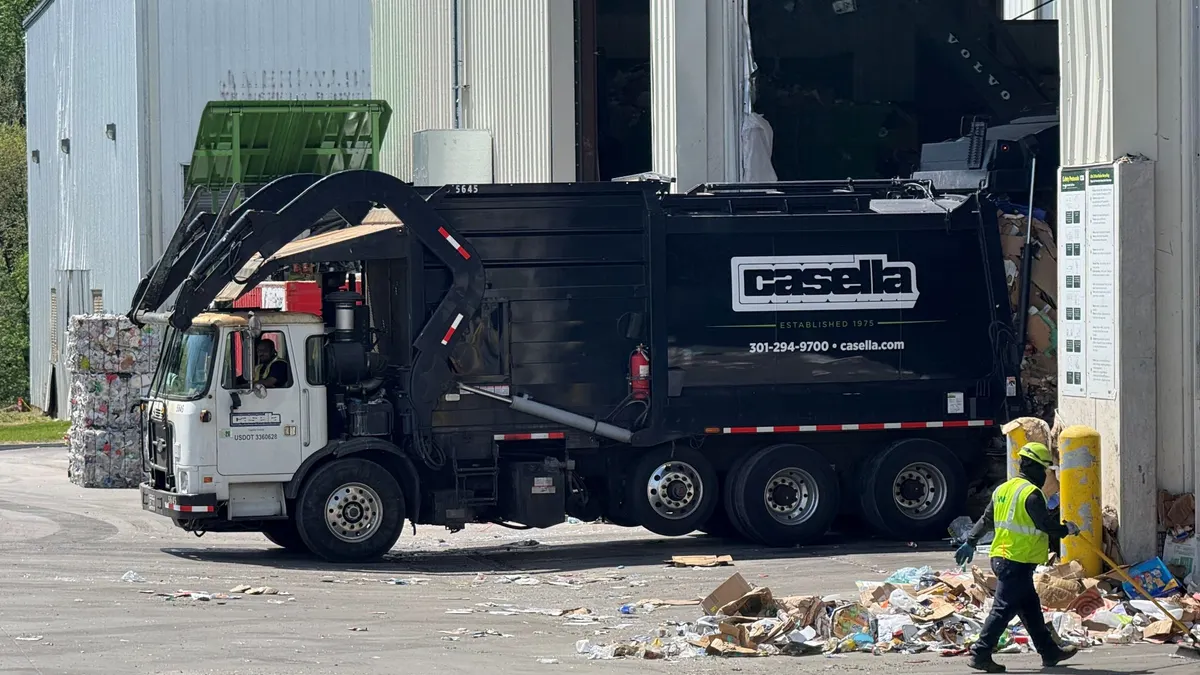
Analysts are keeping a close eye on Casella’s strategy to improve margins after activist investor Jana Partners announced a new position in the company last week.
Jana Partners wants Casella to commit to achieving 27% earnings before interest, taxes, depreciation and amortization margins by 2029. It also wants Casella to hire a performance improvement consultant, Reuters first reported.
For Casella to meet those demands from Jana, analysts say the company must contend with possible headwinds related to its M&A strategy, its smaller size compared to industry peers and other factors.
Casella’s adjusted EBITDA margins have hovered around 23% each year since 2021, despite “strong growth of adjusted EBITDA in dollar terms,” said Trevor Romeo, an analyst with William Blair, in a note to investors last week. Casella’s Q2 adjusted EBITDA margin was 22.7%.
By comparison, Casella’s main solid waste competitors are running margins above 30% and have consistently expanded in the last few years, he said.
Romeo said Casella has some “valid structural reasons” for the difference in margins, such as higher transportation costs in the Northeast, landfill capacity uncertainty and a larger mix of national accounts revenue.
It operates a large brokerage business, which “is a very low-margin business,” added Shlomo Rosenbaum, a managing director at Stifel, in an interview with Waste Dive.
Despite those headwinds, investors have been wanting to see Casella make more meaningful margin improvements to come closer in line with its competitors, Romeo and Rosenbaum said.
William Blair predicts that Casella could reach an EBITDA margin of 23.6% in 2028, though Romeo says that projection is on the “conservative” side.
To get closer to Jana’s requested 27% margin, Romeo estimates Casella would need to focus on realizing at least $30 million of mid-Atlantic synergies, among other efficiencies.
Casella entered the mid-Atlantic market in 2023 with the $525 million acquisition of certain GFL assets in Delaware, Maryland and Pennsylvania. It has since expanded further in the region with the purchase of Whitetail Disposal, LMR Disposal and Mountain State Waste.
The company has spent the last few years trying to optimize the integration of those assets.
The company’s M&A strategy could offer more insight into why margins have not expanded as rapidly as some investors have wanted, investors added. Casella “does the most M&A of anybody relative to their size,” Rosenbaum said, but many of these small acquisitions temporarily dilute margins as the company works to integrate them into Casella’s larger, more consolidated business strategy.
“These companies come usually at lower margins, and so you're constantly layering in lower margin business,” he said. Slowing the acquisition pace could potentially bring up overall margins, but Casella might lose out on strengthening its footprint in the long term.
“If you're filling in a footprint, you'll eventually get them onto your own systems, and then you start integrating them, and you consolidate the routes, and then they do get better,” he said.
During an investment conference last week, Scott Ostfeld, managing partner and portfolio manager for Jana Partners, said it’s possible for Casella to achieve improved margins that drive better returns on a more aggressive timeline. This will “reignite its attractive growth flywheel and unlock Casella’s discounted valuation,” he told Reuters.
Ostfeld added that Casella’s depressed valuation, coupled with its strong reputation and established footprint in the Northeast, could also attract buyers.
Casella’s shares have traded somewhat flat over the past five years and have fallen throughout 2026 while other waste companies in the market have seen better share price performance, Jana has said.
Investor sentiment in Casella has been “dampened” lately due to a combination of investor questions about the company’s recent margins, landfill capacity and general return on invested capital, Romeo noted.
Casella’s share price gained 7.5% soon after Jana announced its stake in the company, Romeo pointed out.
“We believe Casella’s management team is focused on improving these issues, but we are also not surprised that the market is reacting positively on prospects of these efforts being intensified or expedited,” he wrote in the investor note.
Rosenbaum agreed that Casella seems motivated to improve margins. “I do think that we're going to see some movement in that over the next year,” he said.
Casella did not directly respond to questions about Jana’s specific demands. In a statement, Jeff Weld, vice president of communications, said Casella’s management team “strives to maintain open, constructive communications with all of our shareholders, and we welcome and value their input. We remain deeply focused on executing our strategic priorities to drive sustainable, long-term shareholder value creation.”
Jana Partners did not respond to a request for comment.
Casella’s Q3 earnings call is on Nov.10.
Managing Editor Cole Rosengren contributed to this story.